Q2 2026
London residential market report, Q2 2026
A two-speed London: prime central prices are flat while outer zones rise on first-time buyer demand and falling mortgage rates.
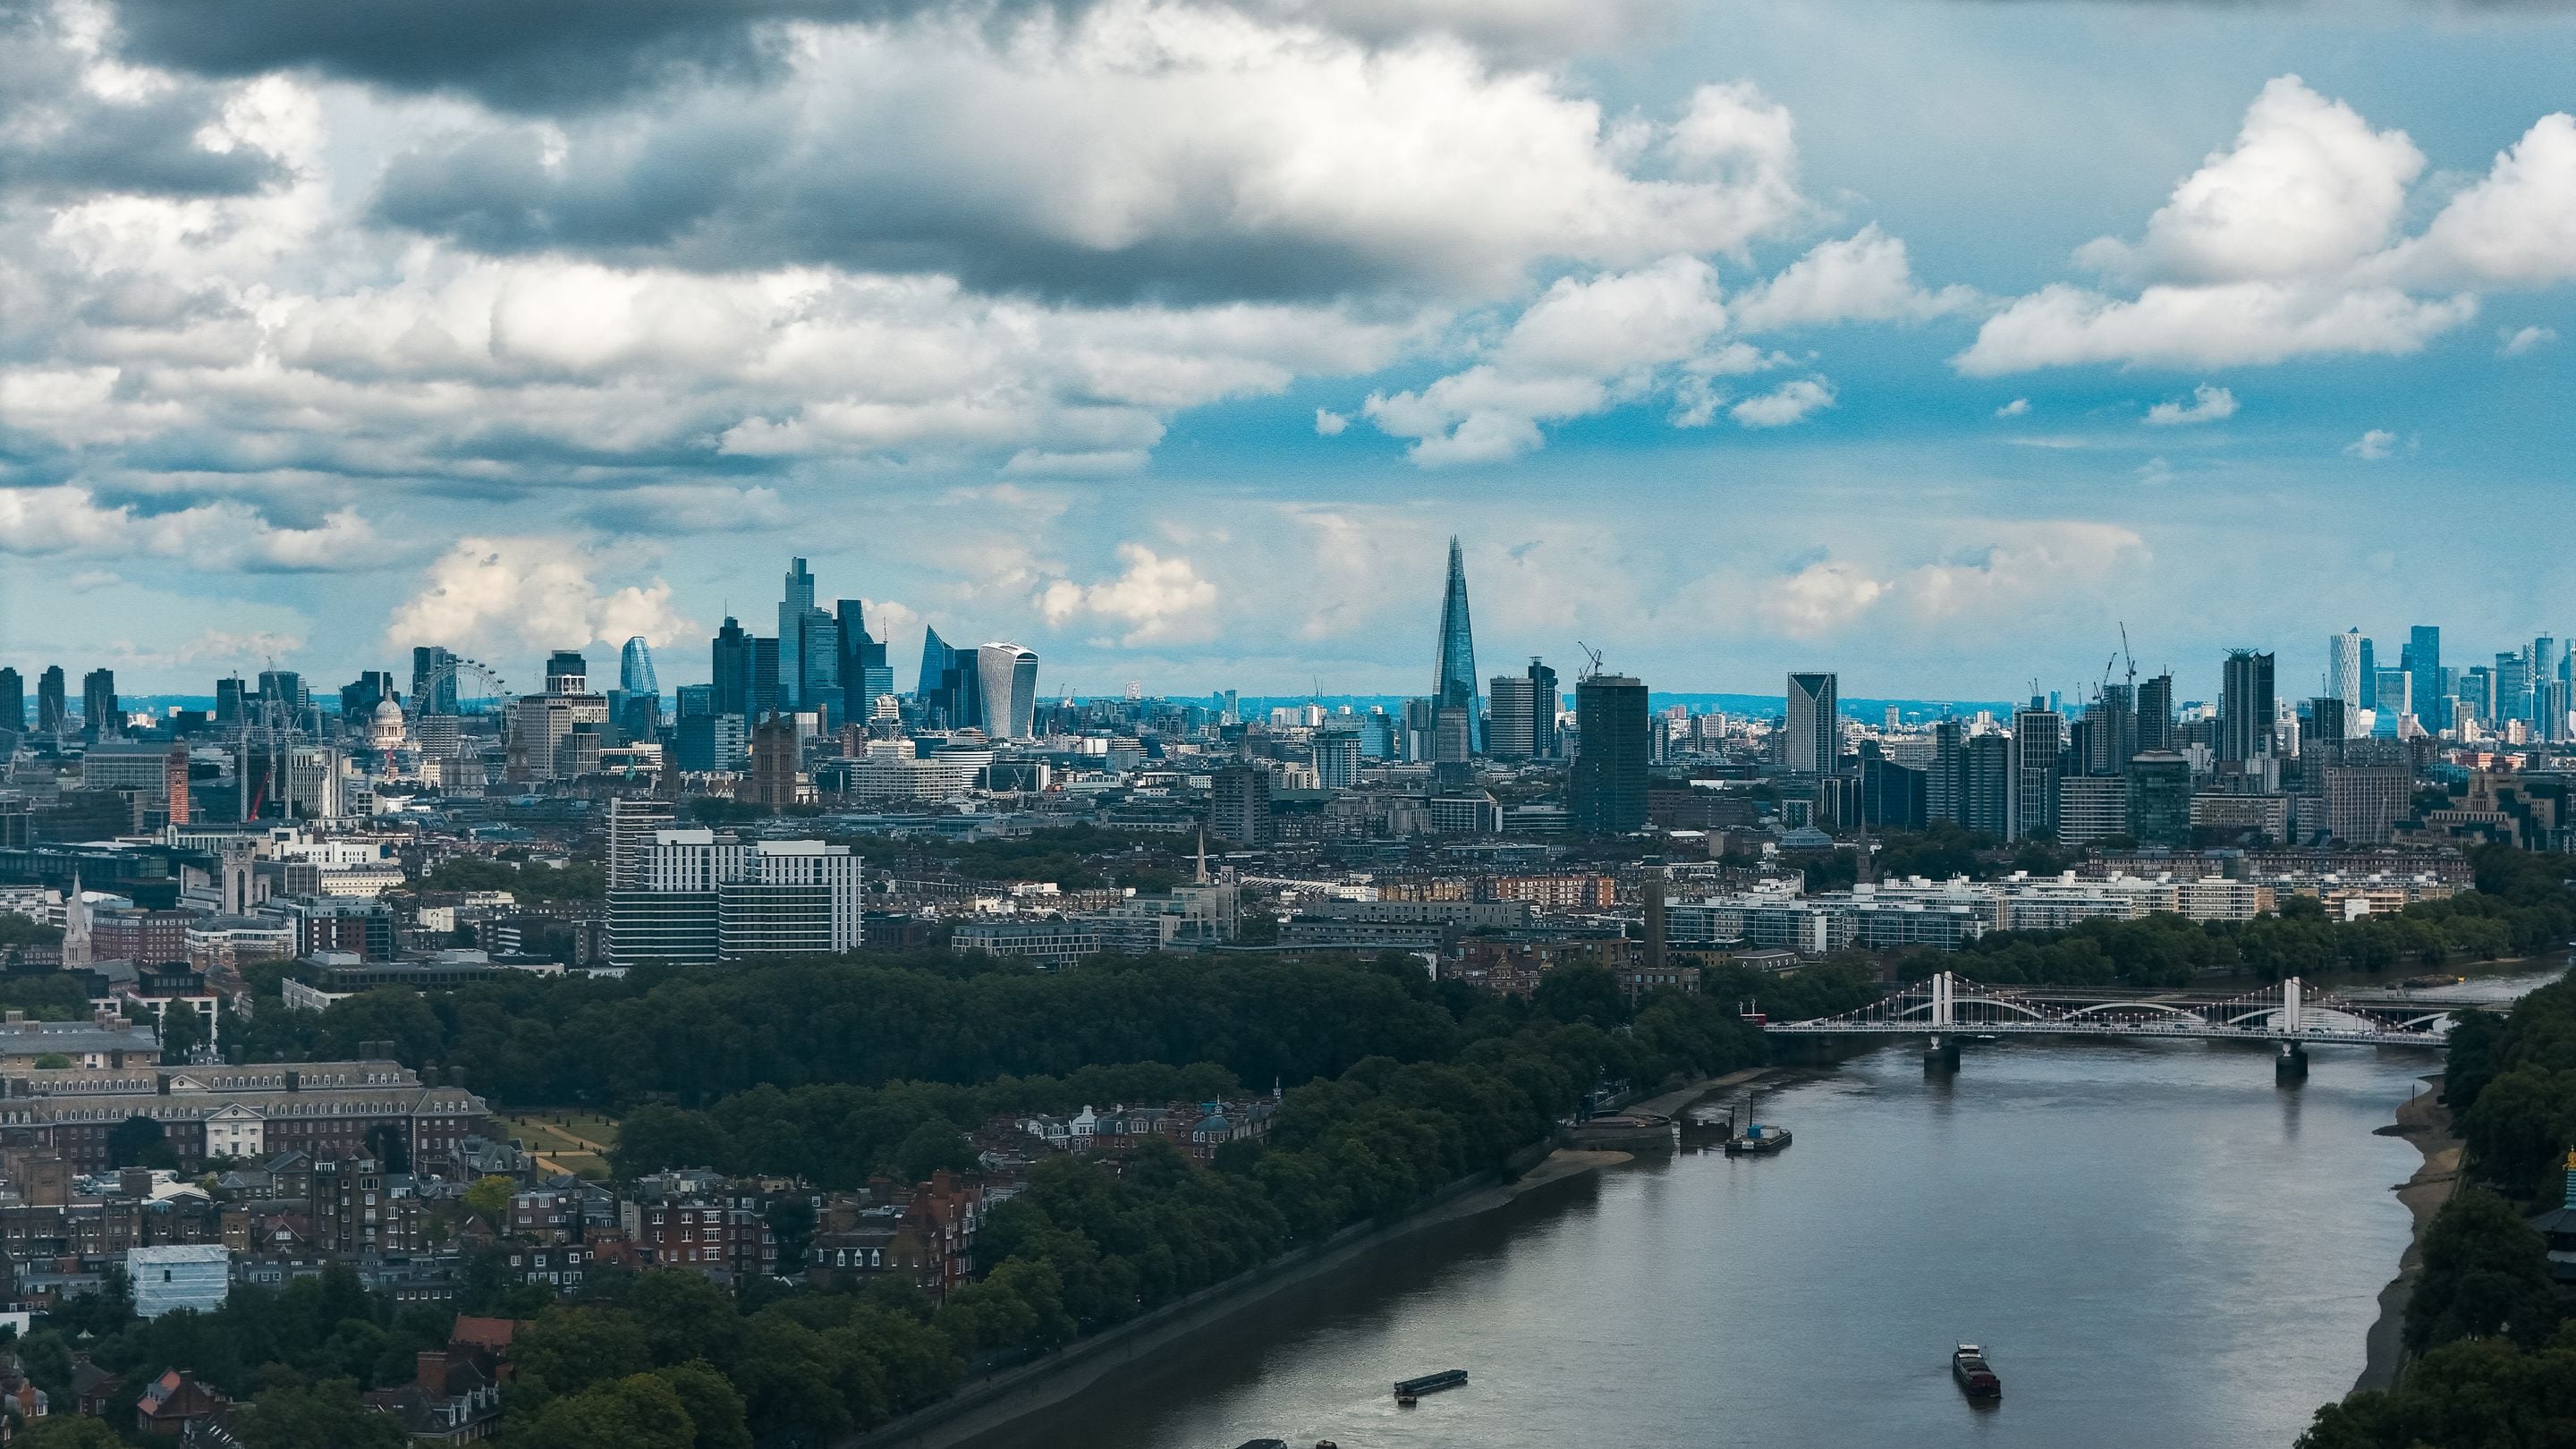
The second quarter of 2026 confirmed a pattern that began in the winter: London sales volumes recovered, mortgage approvals increased and the gap between prime central and outer London widened. This report summarises the quarter for buyers, sellers, landlords and investors.
Sales
The average sale price across the capital rose 2.9 per cent over twelve months to £712,000, with the strongest growth in Zones 3 to 5. Homes priced between £450,000 and £750,000 sold fastest, typically in about four weeks, while properties above £3 million took more than ten weeks.
Kensington recorded flat prices and a 12 per cent rise in the number of homes on the market, giving buyers room to negotiate. In Clapham, stock remained limited and about 30 per cent of sales completed at or above asking price.
Lettings
Average rents increased 4.6 per cent over the year to £2,420 a month, a clear slowdown from the 10 per cent growth recorded two years ago. Demand remained strongest for two-bedroom flats in Shoreditch and Clapham, which let within eight days on average.
The Renters’ Rights Act, which replaces fixed-term assured shorthold tenancies with rolling tenancies, is influencing landlords’ decisions. Some are selling, particularly those with a single investment property and an older mortgage product.
- Mortgage approvals for house purchase rose for a third consecutive quarter
- First-time buyers made up 38 per cent of Halvenor London sales
- Landlord instructions to sell increased by a fifth versus Q1
- The average rental void fell to nine days
Outlook for the second half of 2026
We expect modest growth to continue, with outer London leading and prime central flat. A cut in the Bank of England base rate would support further demand but is already partly priced in by lenders. Buyers should keep their mortgage approvals current, and sellers should price realistically in the first week.
This report is a demonstration document for the fictional Halvenor Realty. All figures are illustrative and must not be used for real decisions.