New York rents settle after the FARE Act, but inventory is the real story
Asking rents flattened over the spring as the broker-fee change worked through the market. Low vacancy still sets the tone for tenants.
Aug 5, 2026 · 3 min read
Ireland’s target of 300,000 new homes by 2030 is the biggest change in Dublin’s market in a generation, but delivery is behind schedule.
October 7, 2026 · 3 min read
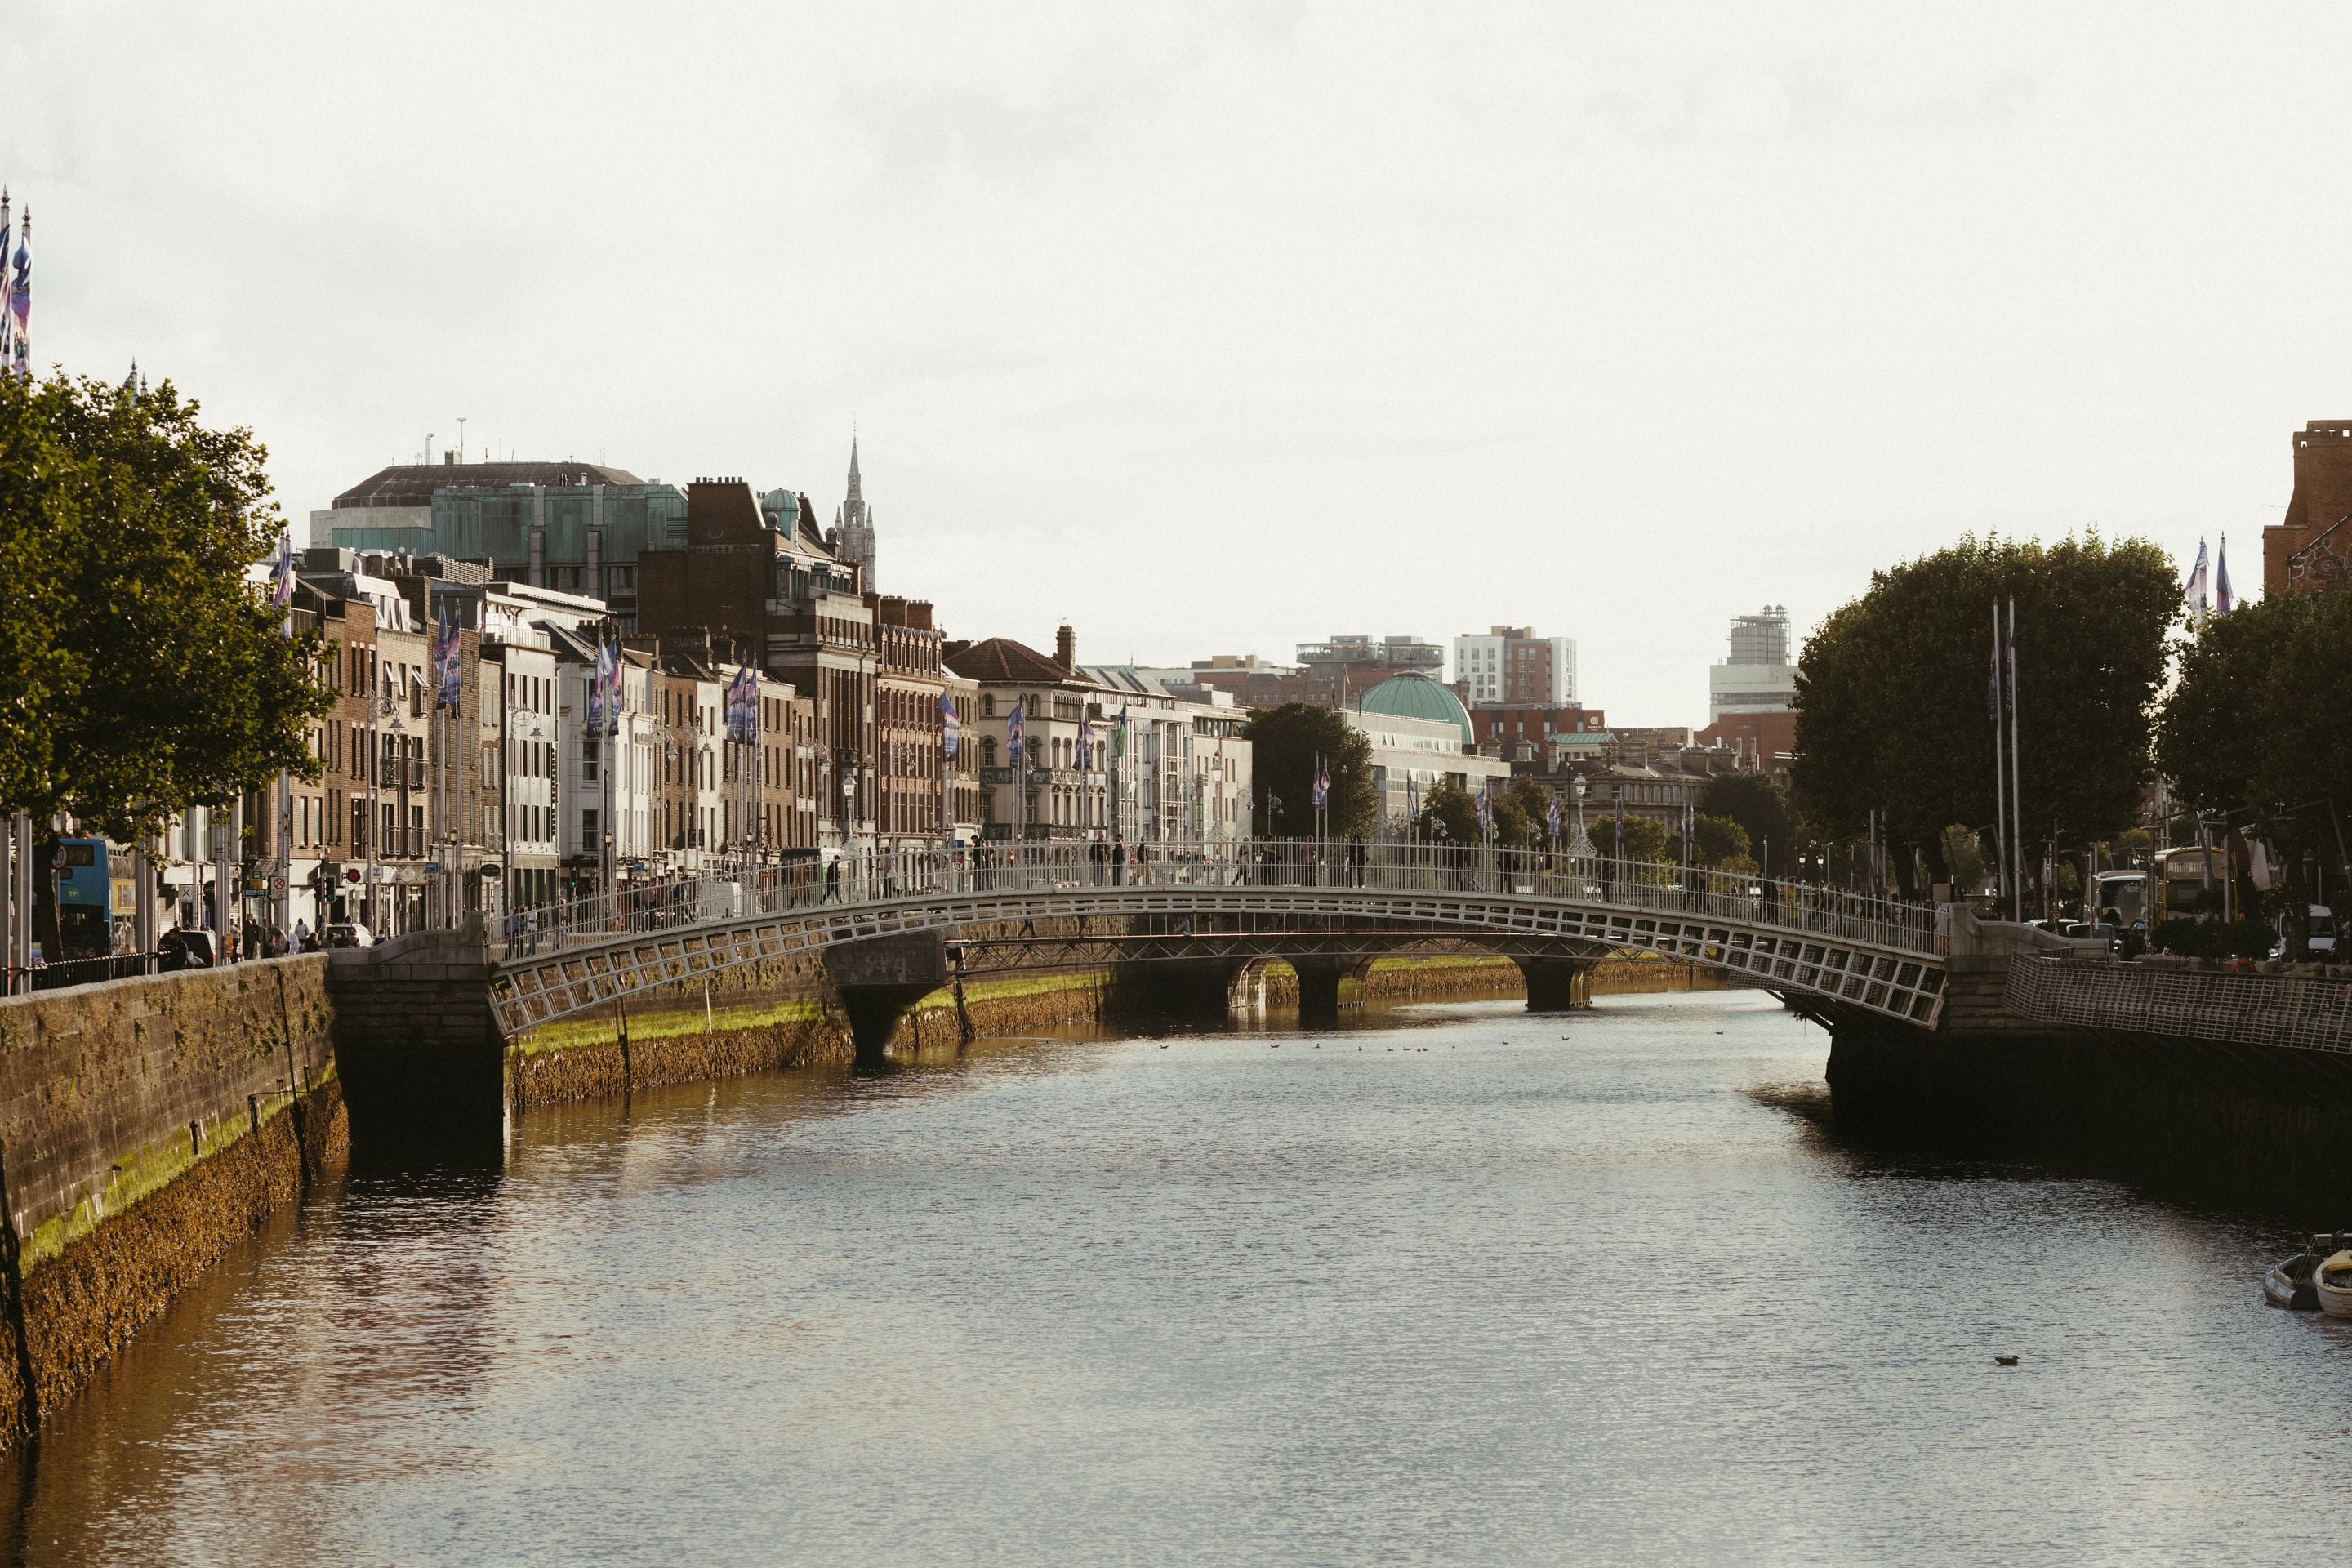
The government’s national plan commits Ireland to building around 300,000 homes by 2030, an enormous undertaking for a country of five million people. In Dublin, the biggest and most expensive market, completions have risen but remain below what the plan requires, and buyers continue to face competition for homes at nearly every price point.
We summarise where Dublin’s market stands in autumn 2026, what help is available for first-time buyers and why we expect the squeeze to continue for at least two more years.
Completions in Dublin rose in 2025, driven by large apartment schemes in the Docklands, Cherrywood and the western suburbs. Despite this, listings for second-hand homes remain at historic lows because owners of houses with low-rate mortgages have little incentive to move. The mismatch means competition persists, with many properties selling above the asking price after a closed-bidding process.
Rents in the capital continue to rise, with average asking rents above €2,300 a month. Tenant protection rules have tightened, reducing the number of private landlords, while larger institutional investors now supply more of the rented stock.
The First Home shared equity scheme lets buyers of new homes cover part of the price with state and bank funding, in return for an equity share. The Help to Buy scheme gives a tax rebate of up to €30,000 for new homes, and the local authority home loan provides low-rate mortgages for those who cannot secure enough from banks. Eligibility rules and price ceilings differ by area, so check them before committing.
Central Bank lending rules cap mortgages at four times gross income for first-time buyers, so household income largely sets the purchase limit. A couple earning a combined €110,000 can borrow up to €440,000 and combine that with savings and incentive schemes to bid for homes in the low-to-mid €500,000 range.
We expect Dublin prices to rise by four to six per cent through 2026, with apartments underperforming houses because of construction costs and viability issues. Buyers who are mortgage-ready and flexible on location will find the process easier. Those who seek a family house in a good school catchment must be prepared for bidding and may need to look slightly further out. Whatever your budget, get your mortgage approval in principle first: sellers and agents in Dublin rarely entertain offers from buyers who cannot show that their financing is in place, and approvals typically remain valid for six months, long enough to search properly without losing time.
The big unanswered question is whether delivery can speed up. Planning delays, judicial reviews, skills shortages and the cost of materials continue to slow construction, and the viability of apartment schemes remains difficult without public support. The government has responded with changes to development levies and with fast-track planning rules, which should help projects reach site within a year or two.
For buyers, this implies two practical strategies. The first is to target new-build schemes where the developer has clear completion dates and the benefit of a state incentive scheme. The second is to widen the search area to commuter towns on rail corridors such as Maynooth, Drogheda and Greystones, where prices are materially lower and journey times are reasonable.
Our Dublin team can explain the incentives in detail and help you work out what you can afford under the current lending rules. Book a free first-time buyer consultation through the contact page.
The figures in this article are illustrative observations from Halvenor’s fictional demonstration desks and are not real market statistics.
Asking rents flattened over the spring as the broker-fee change worked through the market. Low vacancy still sets the tone for tenants.
Aug 5, 2026 · 3 min read
Falling presale activity, rising completions and cautious investors have changed Toronto’s condo market. Buyers have more choice and more leverage than for years.
Aug 26, 2026 · 3 min read
Berlin’s rental market remains tight and its regulation complex. We explain how the rent brake works and why period apartments still command a premium.
Sep 23, 2026 · 3 min read